Welcome to Riley Planning & Investments
The traditional 60/40 stock-and-bond portfolio is still the default at many firms. That mix has struggled to deliver the growth and stability retirees need.
At RPI, we go further.
We diversify beyond stocks and bonds—adding gold, silver, and other assets—to build more resilient portfolios and a more consistent income stream in retirement. We have a proven track record of understanding the economics of what is driving the stock market and how to turn those metrics into results.
2008 showed how quickly a portfolio can be knocked off course.
At RPI, we do not ask you to “ride out” every downturn. We manage investments actively—working to take the sharp peaks and valleys out of the ride so your retirement plan stays intact.
Preserving your account balance becomes even more important in retirement and we are the experts to assist you.
If retirement is close, already here, or suddenly feeling real, we help you decide what to do with your investments, 401(k) plan, income, taxes, and Social Security.
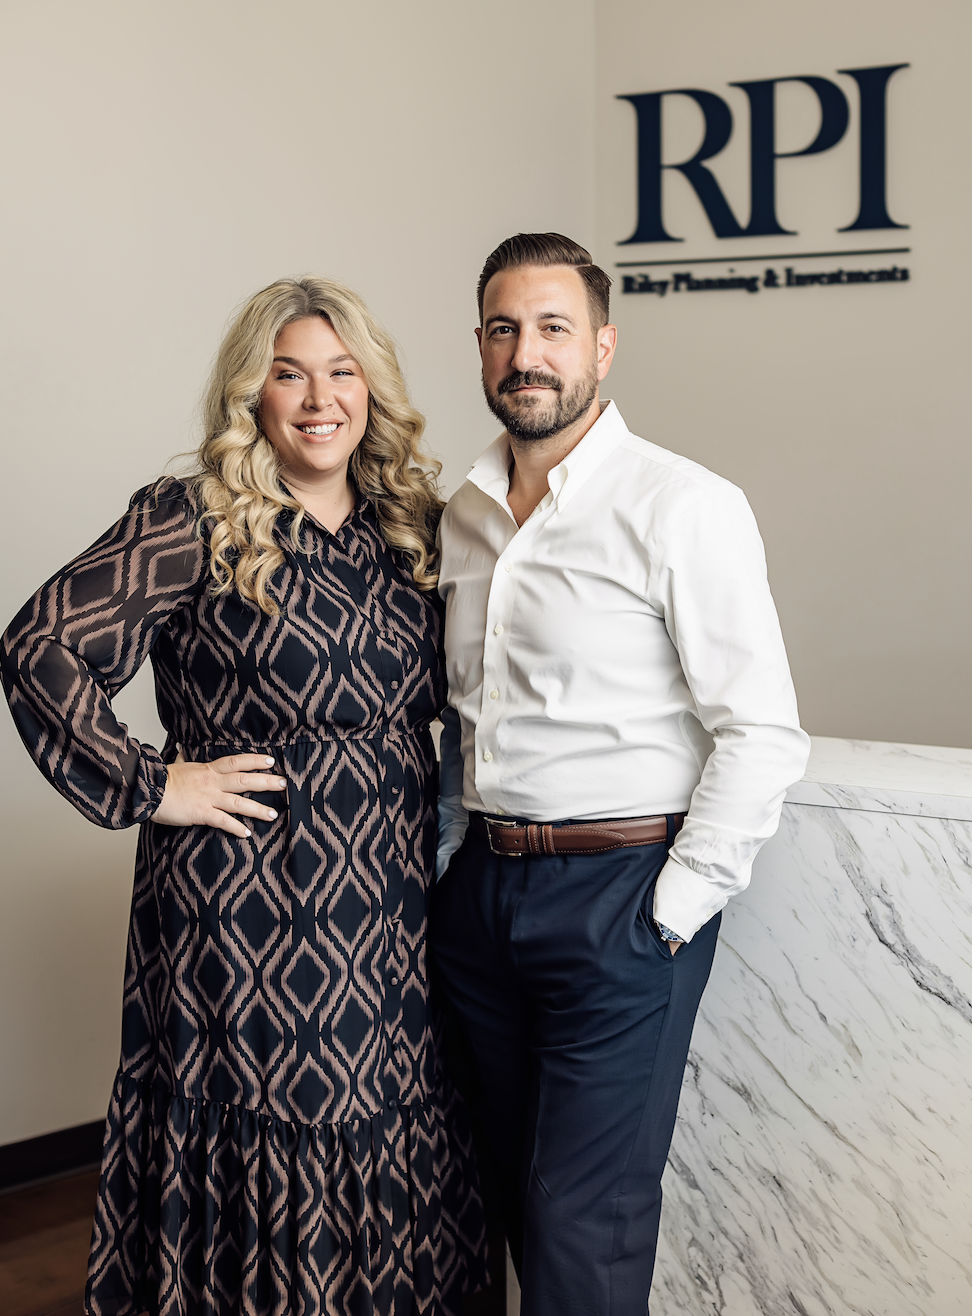
Local to Grand Rapids. You work directly with Jenna and Patrick.
616. 486. 6174
Already have a Financial Advisor? Thats Okay...
You don't have to move your money to talk to us.
See the Difference for Yourself
We encourage you to compare our portfolios with others you are considering. Review the construction, the fees, and the thinking behind each position. We expect ours to stand out.
We believe you'll see the difference.
Jenna and Patrick each have more than 15+ years of experience working in financial services.
They help families across Michigan and have worked with some of the States largest employers including the State of Michigan Pension Plan and Corewell Health.
That dual experience is their edge: they know how to serve people and their individual plans as well as the large group plans they retire through.
As fiduciaries, Jenna and Patrick can evaluate your current retirement plan and investments.
No pressure. No obligation. Just a conversation about where you are, what you're concerned about, and whether a second opinion could help.
Get a second Retirement opinion today:
616. 486. 6174
RPI Services
 Investment Management
As a fee-based financial services firm, RPI delivers personalized investment management that goes beyond simply picking mutual funds. RPI advisors continually analyze the broader economy and market dynamics—because today’s investment landscape is far more complex than the stock market of the past. Proactive strategies incorporating commodities, such as gold and silver, and foreign currencies in an ever-evolving financial world.

Financial Planning
Financial planning is for everyone—no matter your age or stage of life—and it’s a powerful tool to help you take control of your financial future with confidence. Whether you’re just starting your career, building a family, or preparing for retirement, a personalized plan can help you make smarter decisions, reduce stress, and grow your wealth over time. Partner with a trusted RPI advisor today to create a strategy that evolves with you and supports your goals at every stage of life.

Retirement Planning
Retirement planning goes beyond saving—it includes managing investments and taxes effectively in today’s ever-changing financial landscape. As your fiduciary, RPI will provide you with strategies to help optimize your portfolio, reduce tax burdens on your retirement income, and maintain stability while pursuing long-term growth. The result is a resilient retirement plan built to support desired your lifestyle.

Employer Retirement Plans
Whether you need to establish a new 401(k), 403(b), SIMPLE IRA, or SEP IRA—or you already have a plan in place—we can conduct a thorough review and, if it makes sense, transition the plan to RPI. employees. Riley Planning & Investments serves as your Personal CFO for employer retirement plans, providing fiduciary oversight and custom solutions that consider today’s economic complexities.

Social Security Strategies
RPI advisors craft Social Security strategies that reflect current economic conditions and legislative realities. It's important to work with advisors who can help to maximize benefits with clear, tailored guidance suited to today’s financial landscape.
 K-12 and Higher Education Savings
Save for education costs with insightful, tax-advantaged savings strategies designed for today’s economic landscape. The RPI team builds personalized plans to maximize growth and efficiency, so you can confidently prepare for both K–12 and higher education expenses.

Life Insurance and long term care
Life insurance provides financial protection for your loved ones through a tax-advantaged payout. Long-term care insurance helps cover extended care costs while protecting your savings. RPI advisors tailor both to fit your goals and secure your future.

Inheritance Management and Estate Optimization
It's important to have an estate strategy built around today’s complex tax landscape, helping you keep more of what you’ve worked so hard to build. Our approach focuses on minimizing tax exposure and maximizing wealth transfer through personalized, forward-thinking planning. Protect your legacy with tax-efficient strategies designed to benefit you and the generations that follow.

Female-Specific Independence Strategies
RPI advisors offer tailored financial independence strategies for women, combining deep economic insight with personalized planning. Your Personal CFO will empower you to navigate today’s complex financial environment with confidence.
What does your retirement plan need to answer?
If you're looking for answers, we're here to help.