Your 2027 Social Security Raise Is Almost Here. Here's What I Want You to Know
Your 2027 Social Security Raise Is Almost Here. Here's What I Want You to Know
Jenna Riley
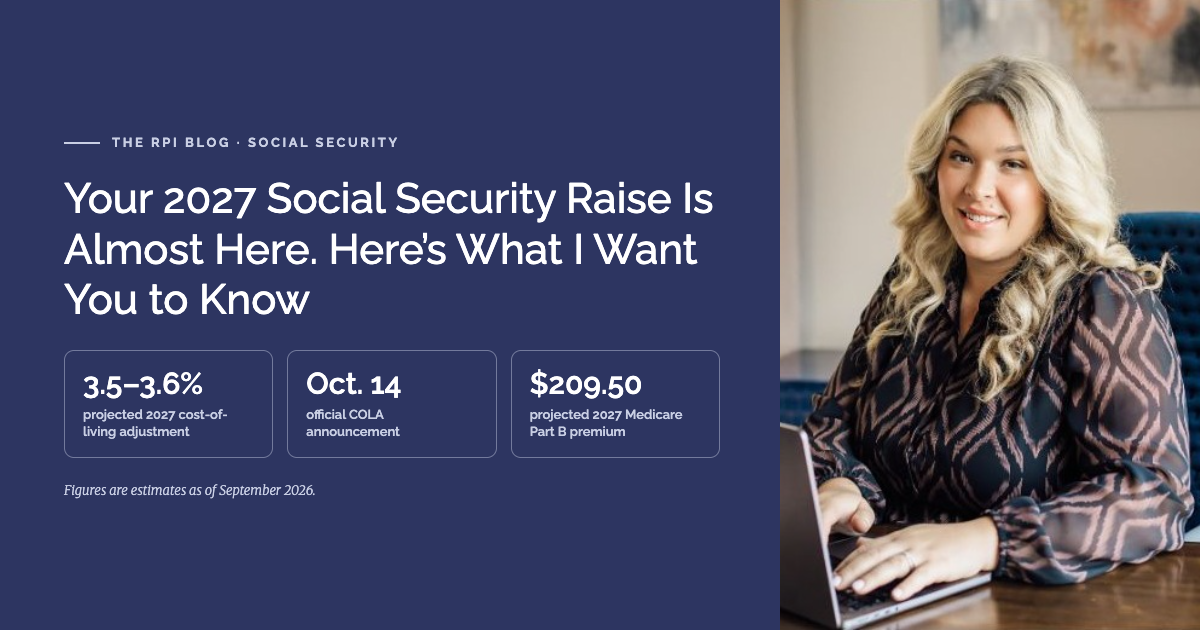
If you've been wondering what next year's Social Security increase will look like, you're not alone. It's one of the questions I hear most this time of year! We'll know the official number soon: the Social Security Administration will announce the 2027 adjustment on Oct. 14, right after the September inflation report comes out. Early estimates are encouraging. With two of the three months used in the calculation now in, forecasts are clustering around 3.5% to 3.6%. That's up from the 2.8% bump for 2026, and it would be the biggest annual increase since 2023.
So what does that mean for your monthly check? The average retired worker received $2,071 a month as of January, so a 3.6% raise would add about $75, bringing it to roughly $2,146 at the start of 2027. I know that feels good, and it should! But I also want to be honest with you. This raise isn't extra spending money so much as a catch-up. Inflation has been all over the place this year. It started at 2.2% in January, climbed to 4.4% in May, then eased to 3.5% in June. If your grocery bill has felt heavier lately, you're not imagining it, and this increase is there to help you keep your footing.
Here's the part that often catches people off guard: Medicare will take a little bit of that raise back. Part B premiums usually come right out of your Social Security check, and the latest Medicare Trustees Report estimates a $209.50 standard Part B premium for 2027. The official number usually comes out later in the fall. If your income is on the higher side, it's worth paying extra attention. Protections that limit premium increases don't apply to everyone, including higher-income beneficiaries who pay income-related surcharges. Those surcharges look back at your income from two years ago. So a Roth conversion or a big IRA withdrawal today can quietly show up in your Medicare costs later. It's exactly the kind of thing I love helping clients plan around ahead of time.
My advice? Use this fall as a gentle check-in on your whole retirement picture. Once the final numbers are out, take a fresh look at your budget. Make sure your withdrawal plan still feels right, and see whether your investments are set up to keep up with rising costs for the long haul. Social Security is just one piece of your plan, and you deserve to feel confident about how all the pieces fit together. If you'd like someone in your corner to walk through it with you, I'd genuinely love to help. Reach out to schedule a complimentary consultation. There's no pressure, just a real conversation about what these changes mean for you.
This information may not be relied on for the purpose of determining your social security benefits or eligibility, or avoiding any federal tax penalties. You are encouraged to seek advice from your own tax or legal professional.